Albert: Budgeting and Banking

Screenshots
Details
- Rating
- 38.90K reviews
- Version
- 10.0.64
- Developer
- Albert - Budgeting & Banking
Analysis by Norviv
I came away from Albert with a fairly clear impression: it is most useful when you want one place to make everyday money decisions feel less scattered. It brings budgeting, banking, saving, and investing into a single finance app rather than asking you to move between several specialist tools. That convenience is its main argument, but it is also the reason to examine it carefully. A broad money dashboard can simplify your routine, yet it may not offer the depth that someone with complicated finances expects.
I tested it with the mindset of someone trying to understand where money goes between paydays, create a little breathing room, and avoid turning financial planning into a second job. The experience feels designed for quick decisions: check what is available, look at upcoming activity, and decide whether a purchase fits. I would recommend it to a person who wants guidance and organization without building a detailed spreadsheet. I would be more cautious with it for anyone who wants advanced investment research, highly customized budgeting, or complete control over every financial category.
What using Albert feels like day to day
The app comes from Albert - Budgeting & Banking and sits in the finance category. It is free to download, carries an Everyone age rating, and supports devices running Android 7.0 or later. Its current version is 10.0.64, so users with older phones should still have a reasonable chance of compatibility, provided the operating system meets that requirement.
Its appeal is not one isolated tool. Instead, the app tries to connect the ordinary pieces of personal money management: spending awareness, a banking experience, saving habits, and investing. That combination makes the first few sessions more useful than opening a blank budgeting worksheet. I can see why the app has reached over 10 million installs, with a 4.4 average from around 160 thousand ratings. Those figures suggest that its straightforward approach resonates with a large audience, though popularity alone does not make it the right fit for every financial situation.
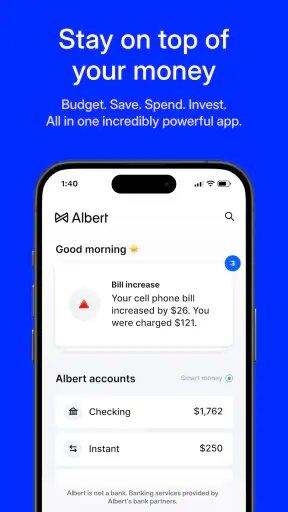
The first practical benefit is reduced friction. When money information is spread across a bank app, a separate savings service, and an investment platform, it becomes easy to lose the overall picture. Albert is built around the opposite idea: bring those decisions closer together so I can review them during the same short session. That matters on a busy morning when I want to check my position before ordering something, not spend twenty minutes reconstructing it from several screens.
I also like the way this approach changes the question from “What did I spend?” to “What can I safely do next?” A historical list of transactions is useful, but it does not automatically help with the next decision. A combined view can encourage me to think about upcoming obligations, current spending, and savings goals as related parts of one plan. For a beginner, that connection is more approachable than a detailed financial model.
Budgeting that works best as a regular check-in
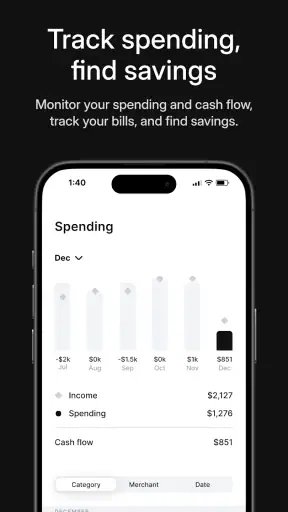
Albert is strongest when I treat budgeting as a frequent habit rather than a once-a-month accounting project. A short check-in can help me notice whether everyday purchases are crowding out a planned saving goal. This is especially helpful for variable spending, such as meals out, transport, entertainment, or small online purchases that seem harmless individually but become meaningful together.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic example is a week before payday. I might see that my regular bills are covered but that flexible spending has been heavier than usual. The useful response is not necessarily to cancel everything. It is to recognize the trade-off early: perhaps I cook at home for a few days, delay a nonessential purchase, or reduce the amount I move toward an optional goal until the next pay cycle. An app that makes this review easy can be more valuable than one with sophisticated features I never open.
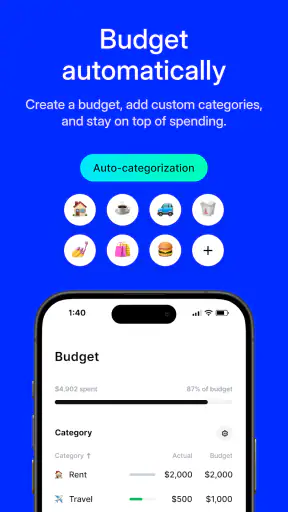
My advice is to establish a baseline before making aggressive changes. Let the app reflect normal activity for a little while, then look for repeated patterns rather than reacting to one unusual transaction. If I immediately label every purchase as a problem, budgeting becomes restrictive and discouraging. Albert works better as a decision aid than as a source of guilt.
There is also a useful psychological distinction between a budget that tells me what I am forbidden to spend and a budget that helps me understand consequences. The latter is more sustainable. I can still spend on something enjoyable, but I have a clearer view of what that choice may postpone. That is a meaningful strength for people who have tried rigid budgeting systems and abandoned them because they felt unrealistic.
Saving requires intention, not just automation
The saving side is appealing for users who struggle to turn good intentions into a repeatable routine. Small, regular actions can be easier to maintain than waiting for a large amount of spare cash at the end of the month. The important point is to choose a target that fits real cash flow. If an automatic saving decision leaves too little room for bills or ordinary surprises, the system will feel like a nuisance rather than support.
I would start with a modest goal tied to a specific purpose: a cushion for irregular expenses, a planned purchase, or a short-term trip. A named reason makes the balance easier to protect than an abstract promise to “save more.” After a few pay cycles, I would review whether the amount still feels comfortable. The app can make the action convenient, but it cannot determine whether the target is sensible for my income and obligations.
This is one area where Albert’s simplicity is both a strength and a limitation. Someone new to saving may appreciate not being confronted with a complicated set of rules. Someone who already manages several goals, different account types, or irregular income may want more customization than a streamlined experience provides. I would not use convenience as a substitute for checking the underlying plan.
Banking and investing broaden the app, but not equally for everyone
Having banking and investing alongside budgeting makes the app feel more complete than a basic expense tracker. It can help a user connect short-term cash management with longer-term financial habits. That is valuable when the alternative is keeping a spending account in one place, savings elsewhere, and investments in a third app that rarely gets reviewed.
Still, “all in one” should not be confused with “best at everything.” A person who wants detailed market analysis, specialist investment research, or advanced portfolio controls may be better served by a dedicated investment platform. Likewise, a user who already has a bank they trust and only needs envelope-style budgeting may find a focused budgeting app easier to understand. Albert’s advantage is the bridge between functions, not necessarily maximum depth in each one.
I would also separate the decision to use the app from the decision to move every part of my financial life into it. Starting with the budgeting and saving workflow can be a sensible way to judge whether the interface suits me. I would only expand my use after I understood how the banking and investing areas fit my needs. That gradual approach reduces the risk of choosing a broad platform simply because it looks convenient at first glance.
The main weakness is the cost of simplicity
The most meaningful drawback is that a simplified financial experience may leave experienced users wanting more visibility and control. When an app combines several money tasks, it has to present them in a way that remains understandable. That usually means some detail is kept behind additional screens or expressed through summaries instead of the precise structure a power user might prefer.
For me, the friction appears when a financial situation is not tidy. Multiple income sources, unusual bill timing, shared household expenses, reimbursements, or a mixture of short- and long-term goals can make a clean overview harder to interpret. A specialist budgeting tool may offer more granular categories and manual adjustments. A traditional bank app may provide a more familiar account-focused view. Albert is more attractive when my needs are broad but ordinary.
There is another practical limitation: an overview is only as useful as my attention to it. A combined dashboard can create the feeling that everything is under control when I have not actually reviewed the details. I still need to check transactions, confirm that goals reflect current priorities, and think about upcoming obligations. No interface can replace that judgment. The app can shorten the process, but it cannot make financial decisions automatically become good decisions.
I would also avoid treating investing as an extension of casual spending. The presence of an investing area may make long-term planning feel accessible, which is positive, but accessibility should not encourage rushed choices. Anyone using that part of the app should understand the difference between money needed soon and money that can remain invested for longer. If that distinction is unclear, a slower learning process is better than acting just because the option is nearby.
Who will get the most from it
Albert is a strong match for someone who wants a friendly starting point for managing money across several areas. It suits a first-time budgeter who finds spreadsheets intimidating, a person who wants a quick view before making everyday purchases, or someone who has saving goals but has struggled to make them consistent. It can also help a user who dislikes switching between separate services and values a single routine more than specialist depth.
The app is particularly practical for people with relatively predictable income and straightforward monthly commitments. In that situation, the combined view can make it easier to see how spending choices affect saving without requiring extensive setup. It is also a good fit for someone who benefits from reminders and regular check-ins, provided they are willing to review the information rather than simply accept every suggestion.
I would point a different user elsewhere if they need detailed household budgeting, complex business and personal separation, extensive manual transaction control, or serious investment analysis. Someone who already has a carefully maintained spreadsheet may find Albert less flexible. A person seeking only a bank account may prefer a traditional banking experience without extra planning features. And anyone uncomfortable with combining several financial activities in one app should take time to decide whether consolidation genuinely improves their routine.
The free price makes experimenting less intimidating, but “free” should not be treated as a reason to skip the normal financial checks. I would read the relevant terms inside the app, understand which services I am choosing, and make sure the experience matches my expectations before relying on it for important decisions. That is not a criticism unique to Albert; it is simply good practice whenever an app touches banking, saving, or investing.
Small habits that make the experience better
My first tip is to use Albert at a fixed point in the week rather than opening it only after a problem appears. A short review after regular income arrives can establish what is available, while another glance before the weekend can catch flexible spending before it gets away from me. This turns the app into a planning tool instead of an emergency monitor.
Second, I would keep short-term and long-term intentions separate in my thinking. Money for an upcoming bill should not be treated like investment money, and a savings goal for a near-term purchase should not be judged by the same standard as a longer-range objective. The app brings these areas together, but I still need to give each one a clear purpose.
Third, I would use the combined view to find decisions, not just totals. If spending is higher than expected, ask which category changed and whether that change is temporary. If saving feels difficult, ask whether the target is unrealistic or whether a recurring expense needs attention. This approach produces an action I can take, which is more useful than staring at a balance without context.
Finally, I would resist making several major changes at once. Adjusting spending, increasing saving, and beginning investing in the same week makes it difficult to know what is sustainable. Albert is most helpful when I use its broad coverage to test one improvement at a time and then observe whether it fits normal life.
My verdict after weighing convenience against control
Albert succeeds because it makes a fragmented money routine feel more connected. Its budgeting, banking, saving, and investing focus gives beginners a practical place to start, and its free availability lowers the barrier to trying that approach. The app’s 39 thousand reviews and large install base reflect broad interest, while the 4.4 average indicates that many users find the overall experience worthwhile.
My recommendation is specific rather than universal: choose it if you want a simple financial companion that helps you check spending, build saving habits, and think about longer-term money in the same general workflow. Do not choose it expecting the detailed control of a specialist budgeting system or the research depth of a dedicated investing platform. Its real strength is connected everyday guidance, not maximum complexity.
For a friend who keeps postponing budgeting because every alternative feels like work, I would suggest giving it a careful trial and beginning with one clear goal. I would ask that friend to review the information regularly, keep important decisions deliberate, and move on if the simplified structure feels too restrictive. Used with those expectations, Albert is a sensible finance app for turning vague intentions into manageable routines, even if more demanding users will eventually want a more specialized tool.
Frequently Asked Questions
01What is Albert: Budgeting and Banking, and what can I use it for?
Albert is a personal finance app designed to bring budgeting, spending insights, saving tools, and banking features into one mobile experience. After connecting eligible financial accounts, you can review transactions, monitor recurring expenses, set savings goals, and see how your spending affects your available money. Features and account options may vary depending on your location, eligibility, and the current terms offered by Albert.
02Is Albert: Budgeting and Banking a real bank, and is my money protected?
Albert provides banking-related services through partner financial institutions rather than operating exactly like a traditional bank in every respect. Before depositing money or using a debit feature, review the app’s current disclosures to identify the program bank, applicable insurance coverage, fees, and account limitations. Protection, eligibility, and availability can depend on the specific product and should not be assumed for every feature.
03Does Albert charge fees or require a subscription?
Some Albert features may be available through a membership or subscription, while other services can have separate conditions, optional charges, or third-party costs. The exact pricing may change, so check the plan details shown during registration and inside the app before accepting an offer. Pay particular attention to membership renewal terms, expedited services, overdraft-related conditions, and any fees associated with banking products.
04Can Albert automatically save money or help me manage my budget?
Albert can analyze connected account activity and use that information to provide budgeting guidance, spending categories, savings suggestions, and other money-management tools. Depending on your settings and eligibility, some features may move money automatically or recommend an amount to save. Automatic actions are convenient, but you should review your cash flow, upcoming bills, and account balance regularly so savings do not create avoidable shortages.
05Is Albert safe to use, and what information does it require?
To provide account aggregation, budgeting, and banking services, Albert may request personal details and permission to connect external financial accounts. The app uses security measures intended to protect account information, but no online service is completely risk-free. Download it only from an official app store, use a strong unique password, enable available security controls, and read the privacy policy to understand how data is collected and shared.


